A customer retention strategy in motor finance is the plan for keeping customers when their agreements end: measuring who renews, reaching them before a rival’s quote does, and giving dealers the tools and coaching to close the renewal. It turns retention from a by-product of good service into a managed sales process.
Few levers in motor finance are as powerful, or as overlooked, as customer retention. Consider a representative book of 100,000 active contracts worth €2.8bn. Nudging the retention rate up by a single percentage point, from 4.59% to 5.59%, adds roughly €28m to the annual value of the book. This is no one-off windfall but a permanent structural gain. The arithmetic, and the means of capturing it, are set out below.
What a retention strategy covers
Retention sits between functions: sales, marketing, captive finance, dealer development and IT. That is why it so often belongs to no one. A strategy gives it an owner and four parts.
- Measure. A retention rate counted by customer, not by contract, defined one way across the business and split by dealer.
- Time. Every account flagged well before its agreement ends, so outreach lands first.
- Act. Dealer teams trained and coached to work the renewal pipeline as a sales process.
- Prove. A value for one point of retention on your own book, and a pilot that shows the return.
The maths
Start with the portfolio.
| Metric | Indicative value |
|---|---|
| Portfolio size | 100,000 active contracts |
| Annual maturing contracts | ~47,000 (half the book each year) |
| Average finance per agreement | €14,000 |
| Portfolio gross yield | ~7.5% a year |
| Average term | 48 months |
| Acquisition-cost saving | ~€250 per retained customer |
A one-point lift retains an extra 470 customers a year. Each is worth more than the headline finance figure suggests:
- Gross margin over the new term: €14,000 × 7.5% × 4 years = €4,200
- Saved acquisition cost: €250
- Total: €4,450 per retained customer
Across a single cohort, 470 extra customers generate some €2.1m in incremental gross margin a year. But retention compounds. As successive cohorts are retained over a four-year cycle, the base of retained customers swells. Sustained across overlapping cohorts, a one-point lift settles at a steady-state addition of €26m–28m in running annual book value. The gain is structural, not transient.
Why motor finance pays
Retention yields fatter returns in motor finance than in ordinary consumer credit, for three reasons.
The first is the size of the ticket. At €14,000 of credit spread over 48 months, each lost customer is a sizeable loss of margin. Preserving an existing account is therefore unusually lucrative.
The second is the rising cost of winning business. Dealer commissions, intermediary fees and compliance keep squeezing front-book margins. The marginal cost of a brand-new customer climbs ever higher; the cost of keeping an existing one is already sunk.
The third is timing. Unlike open-ended subscriptions, motor-finance agreements mature on fixed dates. That creates a clear, observable window in which to secure a renewal—before the customer goes shopping.
Measure it first
None of this can be banked without an honest baseline, and most lenders don’t have one. Contract systems are built around agreements, not people: every new agreement creates a new customer number, so someone financing their third car looks the same as a first-time buyer. Counting contracts instead of customers counts some people twice, and the rate built on it is wrong from the start.
How to measure customer retention in motor finance sets out how to fix that: link every contract to a real customer, use one definition, and split the headline by dealer.
Turning data into renewals
A one- to three-point uplift does not happen by itself. It requires two things working together: visibility of the data, and discipline on the ground.
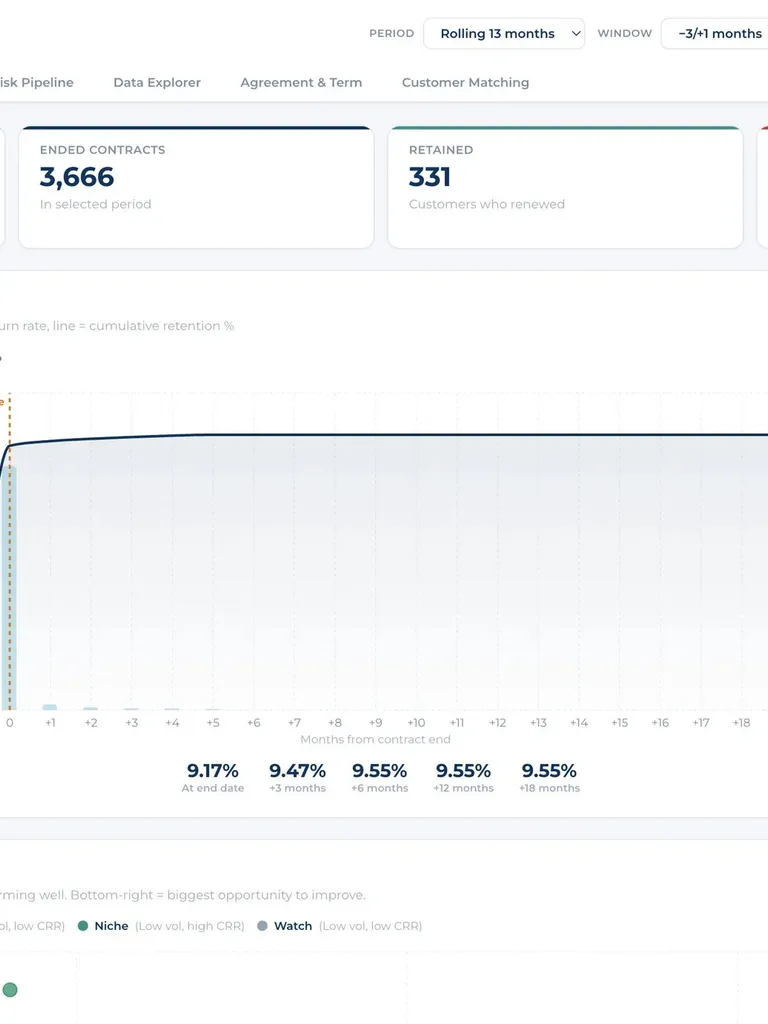
Intelligence. The starting point is reliable data. A retention-intelligence system—here, RetainIQ, part of MobilityIQ—does three things. It measures the customer retention rate at customer rather than contract level, stripping out double-counting and establishing an honest baseline. It flags accounts at six, three and one months from maturity, triggering outreach before rivals’ quotes land. And it isolates vulnerable segments, such as customers at risk of defecting to a dealer, so they can be ring-fenced.
Execution. Data alone changes nothing; people close renewals. The ddx Customer Loyalty Programme supplies the behavioural half through hands-on coaching: training dealer teams to act on the system’s triggers at the right moments; shifting conversations from generic refinance pitches to relationship-driven, competitively priced renewals; and embedding retention as a daily metric rather than an afterthought.
Your next sale is already in your CRM sets out the programme in full, stage by stage.
Proving it
Winning executive backing means nailing down four numbers: the true baseline retention rate, its trend, the points of highest-yield intervention and the hard value of a one-point uplift. A structured pilot establishes all four, alongside operational readiness. It delivers:
- Data and pipeline. A standardised retention rate on a defensible default window, a quantified breakdown of dealer-driven attrition and a ranked, six-month pipeline of at-risk renewals, built from an anonymised data export.
- Financial model. A bespoke valuation of a one-point uplift, calibrated to your own book size and yields.
- Loyalty 360 assessment. An on-the-ground audit of current retention behaviour, processes and capability gaps, to benchmark readiness.
- Live dealer pilots. The programme run across two dealerships, structured to demonstrate behavioural change and a positive return on investment within the trial.
Combine systemic intelligence with behavioural coaching and a theoretical retention target becomes realised portfolio value.
Making the case inside the business
A retention strategy is usually argued for by one person, to colleagues who own other numbers. Three objections come up, and each has an answer.
“The dealers own the customer.” They own the relationship, and a good strategy works with them, not around them. A customer who renews through a different dealer is still retained by the lender, so the strategy has to be clear about who does what. Northridge Finance moved from dealer-led engagement to a structured customer loyalty framework without disrupting dealer partnerships built over decades.
“We already have a retention platform.” Most manufacturer groups already pay for one. Too often the dealer doesn’t use it, doesn’t trust it, or uses it as a reporting tool rather than a sales tool. Software needs coaching beside it to change what happens on the sales floor.
“We can’t prove the return.” Then measure it before committing. A pilot puts a value on one point of retention for your own book, and shows the return in live dealerships. In national pilots, the ddx Customer Loyalty Programme has returned more than 300% on investment.
Ready to size the prize? Get in touch to schedule a portfolio analysis and scope your retention pilot.